Storm Damage & Insurance Claims Handled Right
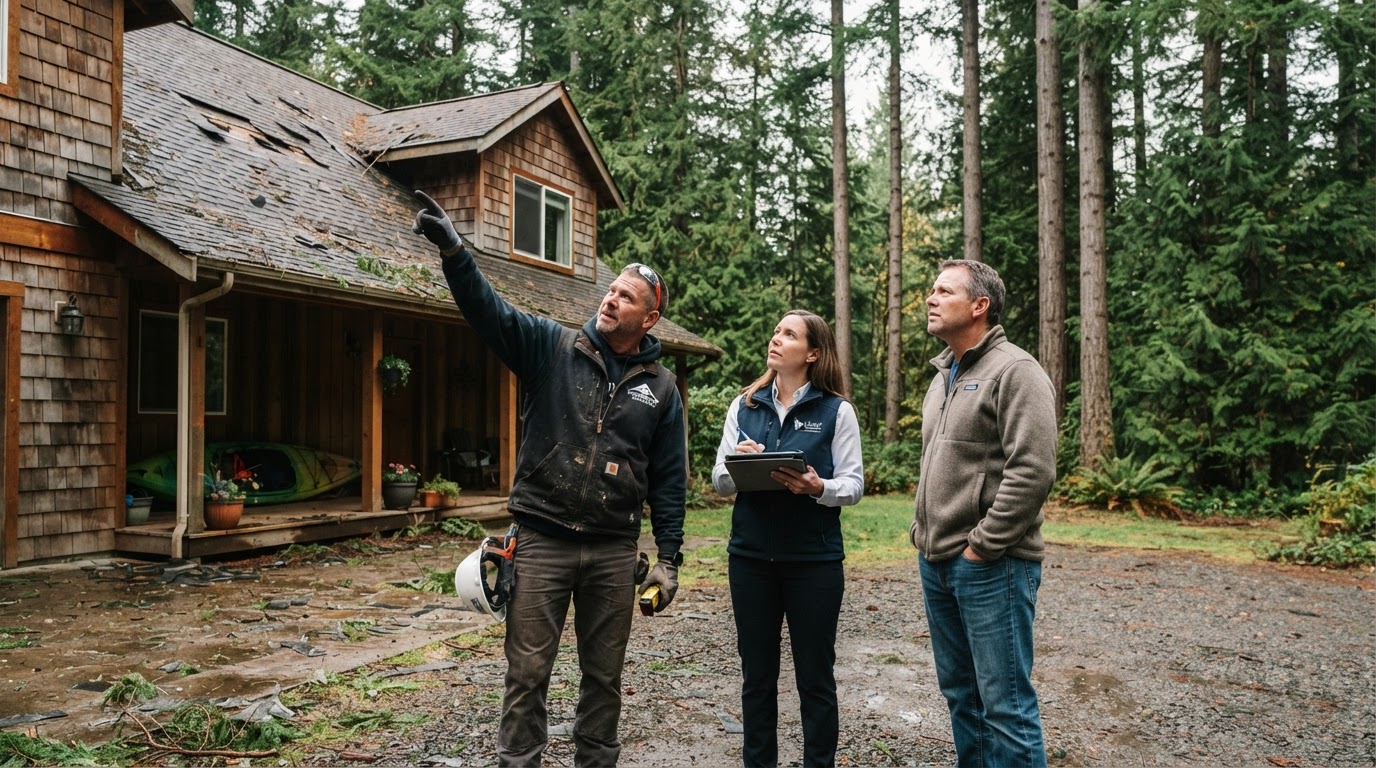
When Pacific Northwest wind, fallen fir limbs, or heavy rains compromise your roof, navigating an insurance claim shouldn't feel like a second disaster. Paul Huppler meets your adjuster on the roof with line-item photo proof so your claim gets approved the first time.
Active Leak or Fallen Tree Limb Right Now?
Insurance policies require immediate mitigation to prevent secondary interior damage. We provide same-day emergency tarping 24/7.
Common Storm Damage Across Puget Sound
Our unique climate combines heavy winter saturations, gale-force wind off the water, and dense tree cover. Here is how storm damage typically manifests on Washington roofs:
Wind Damage & Creased Shingles
PNW windstorms easily reach 50–70 MPH along Puget Sound. When shingles flap in high winds, the fiberglass mat cracks along the top edge — forming an invisible crease that leaks during the very next rain.
Fallen Branches & Impact Punctures
Towering Douglas firs, Western red cedars, and Bigleaf maples surround Northwest homes. Heavy saturated limbs break decking, crush ridge vents, and puncture underlayment.
Wind-Driven Rain & Flashing Pull-Away
Sustained horizontal rain forces water upward beneath lifted shingle tabs and behind compromised sidewall flashing, rotting roof sheathing long before water spots appear on ceilings.
Hail & Micro-Burst Bruising
Spring hail storms bruise shingle granules off the asphalt mat. Granule loss exposes the underlying bitumen to UV radiation and rapid localized deterioration.
How We Handle Your Insurance Claim From Start to Finish
You shouldn't have to become an insurance adjuster just to get your roof fixed. We manage every step so you get full, fair coverage without the runaround.
24/7 Emergency Tarping & Mitigation
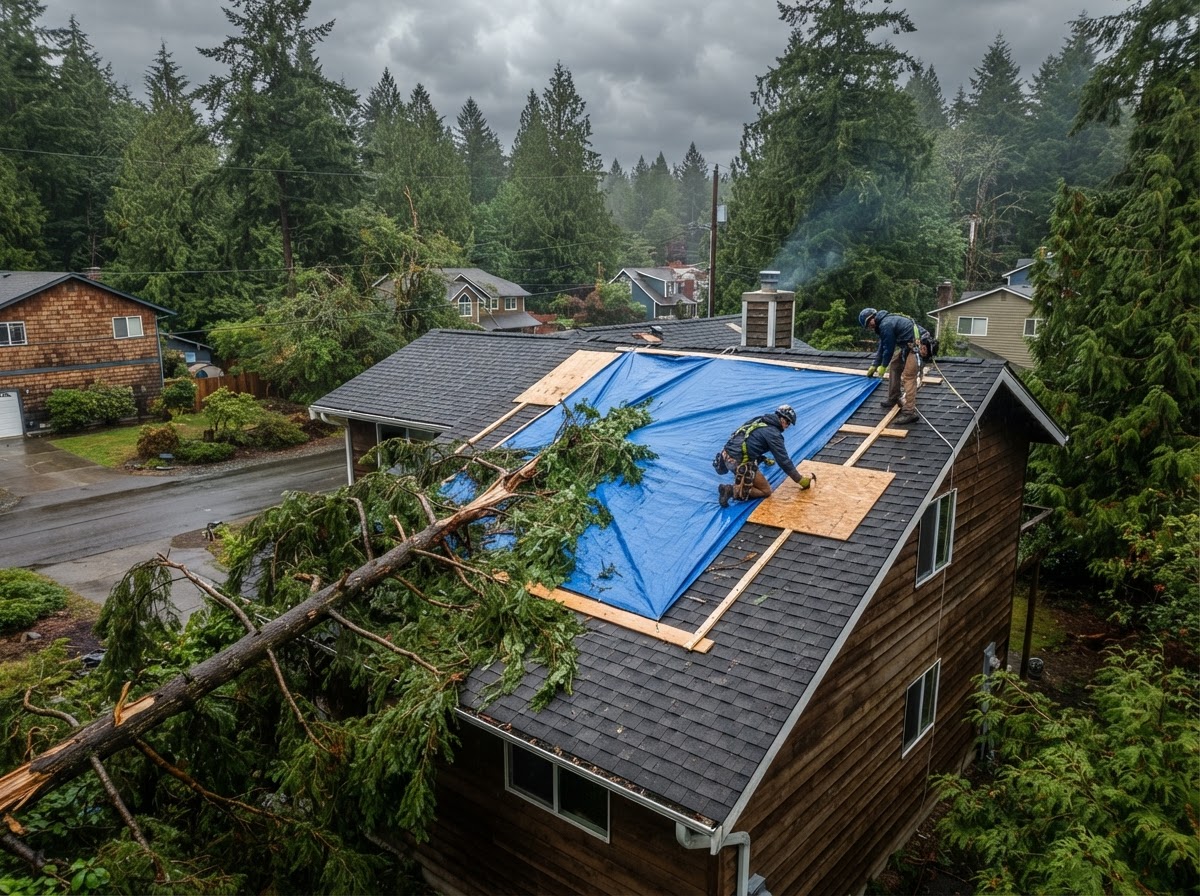
Active water coming in? Fallen cedar limb punched a hole? We secure the opening immediately to prevent interior drywall, insulation, and framing damage — documentation your insurance carrier requires you to mitigate.
Comprehensive Line-Item Photo Inspection
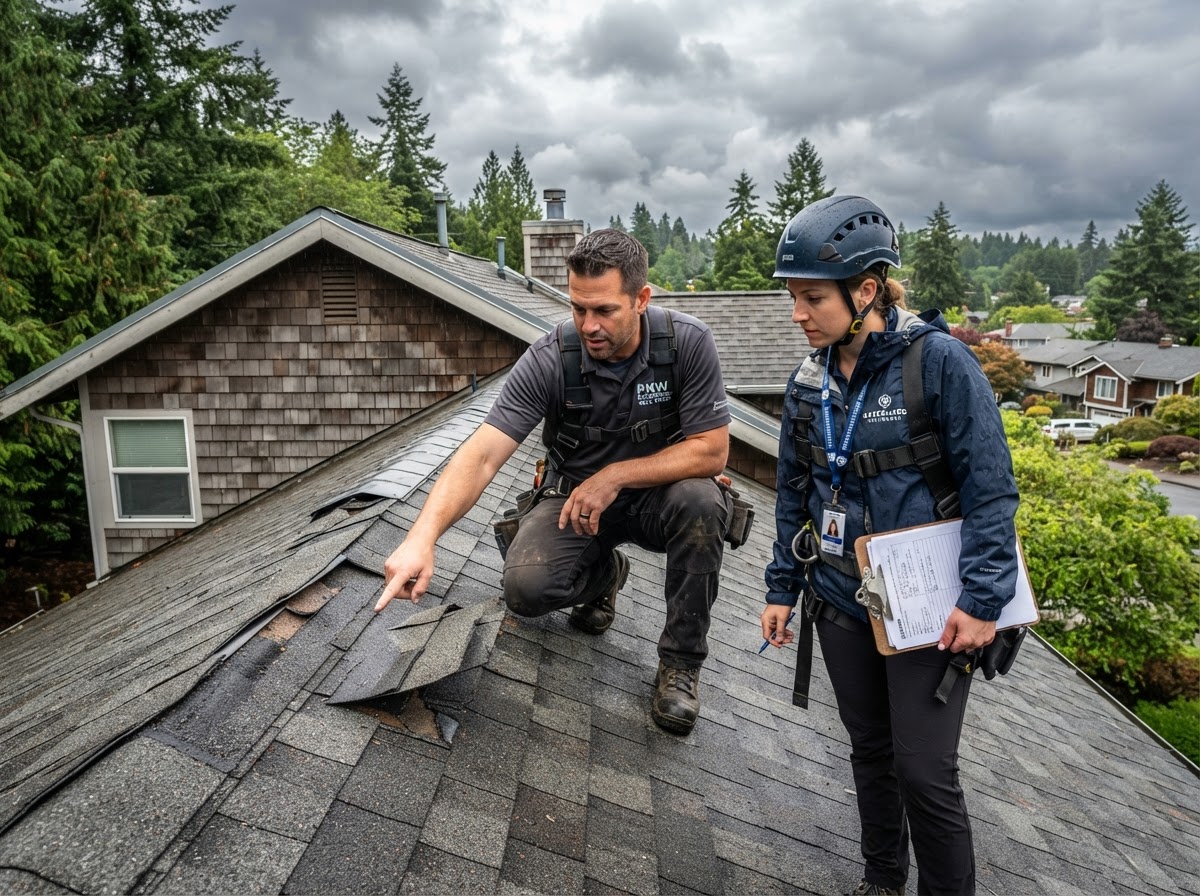
Paul gets up on the roof personally to photograph every creased shingle tab, lifted valley, bruised hail mark, and failed flashing line. Every photo includes GPS metadata, slope orientation, and clear chalk markings.
Adjuster Roof Walk (We Stand With You)
We don't leave you to deal with an adjuster who looks from a ladder. Paul meets the insurance adjuster on your roof, walks slope by slope, and ensures storm-caused collateral damage isn't brushed off as 'pre-existing wear.'
Supplementation & Scope Reconciliation
If the initial adjuster estimate misses ice & water shield, code upgrades, ventilation recalculations, or drip edge requirements, we submit itemized Xactimate-compatible supplements directly to the desk adjuster.
Quality Restoration With PNW Materials
Once the scope is reconciled and approved, we complete the work using proven high-wind, heavy-rain architectural shingles or emergency structural repairs — leaving your yard spotless with magnetic sweeps.
How We Handled The Insurance Claim For Homeowners Like You
From denied claims reversed on re-inspection to emergency branch removals in the middle of the night — here is how Paul advocates for Washington homeowners:
Windstorm in Edmonds: Partial Claim Reversed to Full Replacement
A December Puget Sound windstorm stripped several shingle tabs off Greg's windward roof slope. The adjuster originally wrote a $2,400 estimate for a handful of replacement shingles, claiming the remaining roof was salvageable. Paul got on the roof, performed a brittle test, and documented extensive mat breakage and unsealed thermal strips across both the front and rear facets. Paul met the re-inspection adjuster on the roof, showed him the micro-fractures in person, and the carrier approved a full 32-square architectural replacement with zero out-of-pocket cost beyond their deductible.
Initial Carrier Position
$2,400 patch repair (denied replacement)
Reconciled Carrier Payout
$18,600 full roof replacement approved
Fallen Douglas Fir Branch in Mountlake Terrace
A heavy fir limb fractured 3 rafters and punched through the plywood decking during an overnight storm. Marci called Paul at 6:30 AM. Reconcile was on-site within two hours to remove the branch safely, tarp the breach, and board the interior attic to prevent ceiling collapse. Paul delivered a 24-page line-item photo packet to State Farm that afternoon. Because our mitigation met every carrier emergency guideline, the entire structural repair and matching shingle slope was funded in less than 5 business days.
Initial Carrier Position
Tarping only while waiting 3 weeks for an adjuster
Reconciled Carrier Payout
$14,200 deck framing repair + complete slope reroof
Shoreline Wind & Flashing Failure: Desk Denial Overturned
The carrier's remote desk adjuster denied the claim sight-unseen, claiming water intrusion around the chimney was deferred maintenance. Ron called Reconcile Roofing for a second opinion. Paul climbed the chimney chase, pulled back the counter-flashing, and photographed the violent tear in the step flashing caused by wind-driven framing deflection. Paul wrote a formal rebuttal with side-by-side NOAA wind speed reports from Paine Field. The adjuster reopened the claim, apologized, and funded the complete repair and interior ceiling restoration.
Initial Carrier Position
Initial claim denied as 'wear and tear'
Reconciled Carrier Payout
$11,800 insurance payout covering structural remediation
Why an Adjuster Needs an Advocate on the Roof
Adjusters are under pressure to close files quickly. When Paul is on the roof, nothing gets overlooked.
What Quick Adjuster Walks Miss
- Cracked shingle mats where tabs look flat from the gutter line.
- Deflected chimney and sidewall step flashing pulled loose by wind.
- Sub-surface moisture trapped in soaked plywood sheathing.
- Building code upgrade requirements (ice & water shield, drip edge).
What Paul Huppler Documents & Wins
- High-resolution close-up photos of cracked matting and torn sealants.
- ITEL shingle laboratory tests proving discontinued matching materials.
- Official NOAA weather station wind speed and hail storm reports.
- Line-item Xactimate scopes including all WA municipal code items.
Roof Insurance Claims in Washington State
Clear, straight answers to the questions Puget Sound homeowners ask most.
Will filing a roof storm damage claim make my insurance rates go up?
Under Washington state insurance regulations, claims resulting from an Act of God or severe weather (wind, hail, fallen trees) cannot be used as the sole reason to raise an individual homeowner's premium. Insurance rates are set regionally by risk pool. If a major storm hits your neighborhood, rates often adjust for the entire ZIP code regardless of whether you file — so leaving legitimate roof damage unfixed only hurts your home's equity.
Why do I need Paul on the roof when the insurance adjuster visits?
Insurance adjusters frequently inspect 4 to 6 homes a day. Many are independent contractors who look from a ladder or walk only the most accessible slope. Paul has 28+ years of Pacific Northwest roofing experience and knows where storm damage hides: cracked fiberglass mats beneath seemingly flat shingles, lifted valley underlayment, and deflected flashing seams. Having an experienced advocate on the roof ensures every damaged square is documented and counted.
What should I do immediately after a storm damages my roof?
First: call us for 24/7 emergency tarping if water is entering your home. Insurance policies require homeowners to mitigate secondary interior damage. Second: do not climb onto a wet, steep roof yourself — let us take the high-resolution photos. Third: notify your carrier to establish a claim number, and tell them Paul Huppler at Reconcile Roofing is your contractor of record.
What if the insurance company only offers a partial repair, but my shingles are discontinued?
This is one of the most common issues in Washington. If your shingle is discontinued or cannot be matched in size, color, or exposure, patching creates a mismatched roof that violates building code and diminishes property value. We run shingle identification reports through ITEL and submit them to your carrier to advocate for a full roof replacement.
How does payment work with an insurance claim?
The insurance carrier typically issues payment in two checks: the Actual Cash Value (ACV) check upfront, and the Depreciation check after the work is completed. You are only responsible for your policy deductible. We work directly with your insurer's paperwork so there are no surprise fees or out-of-pocket costs beyond your agreed deductible.
Let Us Reconcile Your Storm Claim.
Have storm damage or want a professional second opinion before your adjuster arrives? Submit your details below or call Paul directly.
24/7 Storm & Emergency Line
425-448-8383
Immediate tarping dispatch available
Send Us Your Insurance Documents
ReconcileRC@gmail.com
We review adjuster scopes at no charge
Licensed & Bonded
WA Contractor License #RECONRL816N6
28+ Years of Pacific Northwest Roofing Experience
Schedule a Storm Inspection
Select "Storm Damage" below and Paul will reach out promptly to coordinate with your adjuster.